In a consumer-driven world, our wallets are constantly under attack. From targeted social media ads to one-click checkout options, the friction between seeing a product and buying it has never been lower. This constant barrage of purchasing opportunities often leads to a cluttered life, both physically and financially. If you find yourself living paycheck to paycheck despite earning a decent income, or if you simply feel overwhelmed by your financial obligations, it might be time to strip your spending down to the absolute essentials.
Enter the minimalist budget challenge. This is not about depriving yourself of joy or living a life of extreme austerity. Rather, it is a deliberate, strategic approach to personal finance designed to separate your genuine needs from your fleeting wants. By committing to this challenge for a dedicated period, you can gain profound financial clarity, eliminate unnecessary stress, and redirect your hard-earned money toward what truly matters. As a financial advisor, I have seen countless individuals transform their financial trajectories by adopting this mindset. This comprehensive guide will walk you through the philosophy, the step-by-step execution, and the long-term wealth-building strategies that follow a successful minimalist budget challenge.
The Philosophy Behind the Minimalist Budget
Before diving into the mechanics, it is crucial to understand the mindset required for this challenge. The minimalist budget focuses on removing excess spending to free up capital for important life goals. It acts as a financial filter, helping you distinguish between expenses that add genuine value to your life and those that have simply crept into your daily habits through unconscious repetition.
When you apply minimalism to your finances, you are not just managing money; you are managing your attention and your energy. Every dollar spent on an impulse purchase is a dollar stolen from your future freedom. This approach reduces the psychological stress caused by overspending and the physical clutter of unnecessary purchases. The core idea is to make spending choices based on long-term value and purpose rather than short-term dopamine hits. It is a lifestyle shift that builds discipline, fosters personal growth, and ultimately gives you total control over your financial direction.
The 10-Step Minimalist Budget Challenge
To successfully implement this strategy, follow this proven ten-step framework.
Step 1: Understand and Commit to the Approach
The first step is entirely mental. You must fully commit to the idea that less is more. Acknowledge that your current spending habits may be flawed and that a reset is necessary. Write down your “why.” Are you trying to pay off student loans? Save for a house? Build an emergency fund? Having a clear, compelling reason will anchor you when the challenge gets difficult.
Step 2: List All Current Monthly Expenses Clearly
You cannot manage what you do not measure. Begin by conducting a comprehensive financial audit. Print out your bank and credit card statements for the last 90 days. Write down every single expense, leaving nothing out. Include fixed costs like rent, mortgage, utilities, and insurance, as well as variable costs like groceries, dining out, subscriptions, and hobbies. Seeing the full list in one place is often a shocking revelation. It exposes the “leaks” in your budget—small, recurring drains that you no longer even notice.
Step 3: Define True Needs Versus Wants Honestly
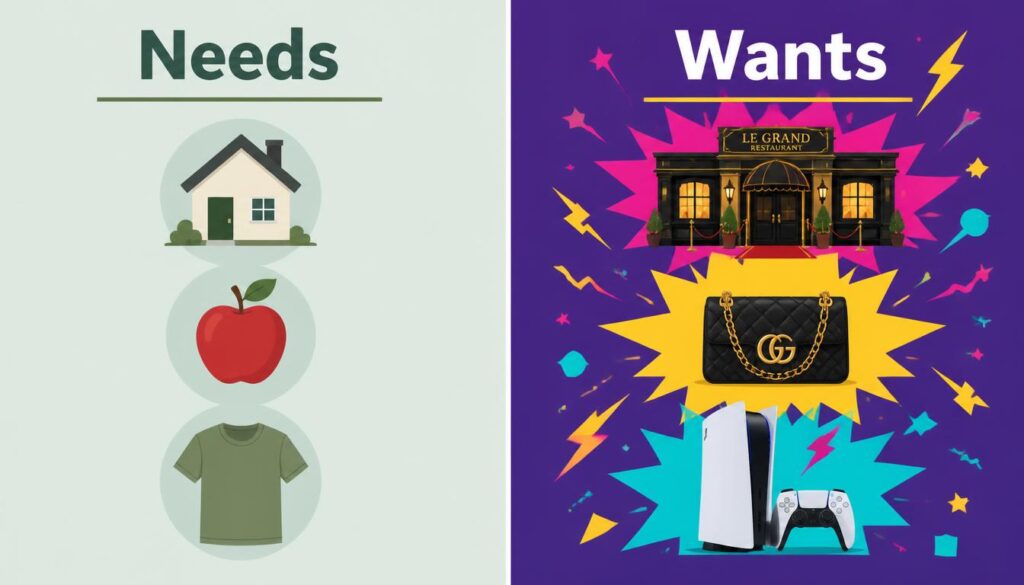
This is the most critical analytical step. A “need” is something essential for survival, basic health, and maintaining your ability to work. This includes basic nutritious food, secure shelter, essential utilities, basic clothing, and transportation to your job. A “want” adds convenience, style, entertainment, or luxury. It includes dining at restaurants, streaming services, designer clothes, and the latest electronics. Be ruthlessly honest. Marketing is designed to make wants feel like needs. If you can live without it and your basic life functions are not impaired, it is a want.
Step 4: Cut or Reduce Non-Essential Purchases
Once you have categorized your expenses, it is time to take action. Start by completely eliminating the most obvious non-essentials. Cancel unused gym memberships, pause subscription boxes, and delete shopping apps from your phone. For things that are hard to cut entirely, reduce them. If you eat out five times a week, cut it to one. If you buy premium coffee daily, switch to brewing at home. The goal is to drastically reduce the outflow without completely destroying your quality of life.
Step 5: Create a Monthly Minimalist Budget Plan
Now, build your new budget from the ground up. Use a zero-based budgeting method, where every dollar is assigned a job before the month begins. Fund your absolute essentials first: housing, utilities, basic groceries, and transportation. Next, allocate your minimum debt payments. Finally, assign a specific, aggressive amount to your savings and investment goals. If there is any money left over, it can be used for a highly restricted “fun” category, but keep it minimal. This structure ensures your priorities are funded first.
Step 6: Track All Spending Against the Plan
A budget is only as good as your adherence to it. Track every single penny you spend. You can use a dedicated budgeting app, a simple spreadsheet, or the traditional envelope system. The act of tracking creates immediate accountability. When you have to manually log a $6 coffee purchase, you become hyper-aware of your spending. Review your tracking daily or every few days to ensure you are not drifting outside your minimalist guidelines.
Step 7: Redirect Savings Toward Important Goals
This is where the magic happens. The money you are saving by cutting out wants should not just sit in a checking account where it might be accidentally spent. Redirect it immediately into specific financial vehicles. If you have high-interest debt, throw every extra dollar at it using the debt avalanche or snowball method. Once your high-interest debt is gone, build a fully funded emergency fund of three to six months of expenses in a High-Yield Savings Account (HYSA).
Step 8: Invest for Long-Term Wealth
Once your emergency fund is secure and high-interest debt is eliminated, transition your redirected savings into investing. Open a brokerage account or maximize your employer-sponsored retirement plan (like a 401(k) or IRA). Focus on low-cost, diversified index funds or Exchange Traded Funds (ETFs) that track the broader market. By consistently investing the surplus generated by your minimalist budget, you allow compound interest to work its magic, turning your daily sacrifices into generational wealth.
Step 9: Avoid Lifestyle Creep
Lifestyle creep is the silent killer of wealth. It occurs when your income increases, and your spending automatically rises to match it, leaving you no better off than before. If you get a raise, a bonus, or a tax refund, do not upgrade your car or move to a more expensive apartment immediately. Maintain your minimalist budget. Direct the extra income entirely toward your investment and savings goals. This discipline is what separates the truly wealthy from those who just look wealthy.
Step 10: Review, Adjust, and Celebrate
Life is dynamic, and your budget should be too. Review your minimalist budget at the end of every month. Adjust for seasonal changes, unexpected expenses, or shifts in your income. If a specific cut is causing you immense misery and leading to binge spending, adjust it slightly. Finally, when you hit a major milestone—like paying off a credit card or reaching a savings goal—celebrate! Do it in a way that doesn’t cost money, like a hike in nature or a homemade feast. Acknowledging your success reinforces the positive habits.
The Hidden Benefits of Minimalist Budgeting
While the primary goal of this challenge is financial improvement, the secondary benefits are equally profound. Financial minimalism drastically reduces decision fatigue. When you eliminate the constant temptation to buy, you free up mental bandwidth to focus on your career, your relationships, and your personal growth.
Furthermore, it promotes environmental sustainability. By consuming less, you are reducing your carbon footprint, minimizing waste, and opting out of the fast-fashion and disposable-goods cycles. You begin to appreciate the things you already own, finding joy in utility and simplicity rather than the endless pursuit of the next new thing. This shift in perspective often leads to a deeper, more enduring sense of happiness that material goods simply cannot provide.
Common Pitfalls and How to Overcome Them
The Deprivation Mindset: Many people fail because they view the minimalist budget as a punishment. Reframe your thinking. You are not giving up things you need; you are giving up things that do not serve you. Focus on what you are gaining (freedom, security) rather than what you are losing.
Social Pressure: It can be difficult to say no when friends want to go to an expensive restaurant or plan a lavish weekend trip. Be honest about your goals. True friends will respect your financial boundaries. Suggest alternative, low-cost activities, like hosting a potluck dinner or going for a run together.
Unexpected Expenses: An emergency can derail your budget if you are not prepared. This is why building even a small starter emergency fund of $1,000 should be your very first priority before aggressively paying down debt or investing.
Conclusion
The minimalist budget challenge is more than just a temporary restriction on your spending; it is a fundamental reset of your relationship with money. By systematically identifying your true needs, ruthlessly cutting out the non-essentials, and redirecting your resources toward wealth-building, you take back control of your financial destiny. It requires discipline, honesty, and a willingness to delay short-term gratification for long-term freedom. However, the rewards—financial clarity, reduced stress, and the compounding growth of your investments—make every moment of the challenge entirely worth it. Start today, track your progress, and watch as your minimalist choices build a maximized future.
Frequently Asked Questions (FAQ)
1. How long should I commit to the minimalist budget challenge?
While you can do it for a single month to reset your habits, it is highly recommended to adopt it as a long-term lifestyle. If a month feels too daunting, start with a 14-day challenge to prove to yourself that it is possible, then gradually extend it. The ultimate goal is to make minimalist spending your permanent baseline.
2. What is the difference between a minimalist budget and extreme frugality?
Extreme frugality often involves depriving yourself of basic comforts and focusing solely on hoarding every penny, which can lead to burnout. A minimalist budget, on the other hand, focuses on intentionality. It allows you to spend generously on the things that truly bring you value and joy, while completely eliminating spending on things that do not matter to you.
3. How do I handle social events and dining out on a minimalist budget?
Socializing is a human need, but expensive dining out is a want. You can still maintain a social life by hosting potluck dinners, suggesting free activities like hiking or visiting museums on free days, or setting a strict, pre-planned budget for the occasional night out. Communicate your financial goals to your friends so they understand and support your choices.
4. What is the best way to invest the money I save from this challenge?
Once you have a fully funded emergency fund in a High-Yield Savings Account, the best approach for most people is to invest in low-cost, broadly diversified index funds or ETFs (like those tracking the S&P 500 or the total stock market) through a tax-advantaged retirement account like an IRA or 401(k), or a standard brokerage account. This provides steady, long-term growth with minimal effort.
5. Can I still enjoy hobbies on a minimalist budget?
Absolutely. The minimalist budget is not about eliminating joy; it is about eliminating waste. If a hobby brings you deep satisfaction, allocate a specific, reasonable amount of money for it in your budget. The key is to ensure that the spending on the hobby does not compromise your essential needs or your long-term financial goals. You may just find that you enjoy your hobbies more when you are more intentional about how you fund them.